Trump’s Shifting Economic Policies Challenge Long-Standing Norms
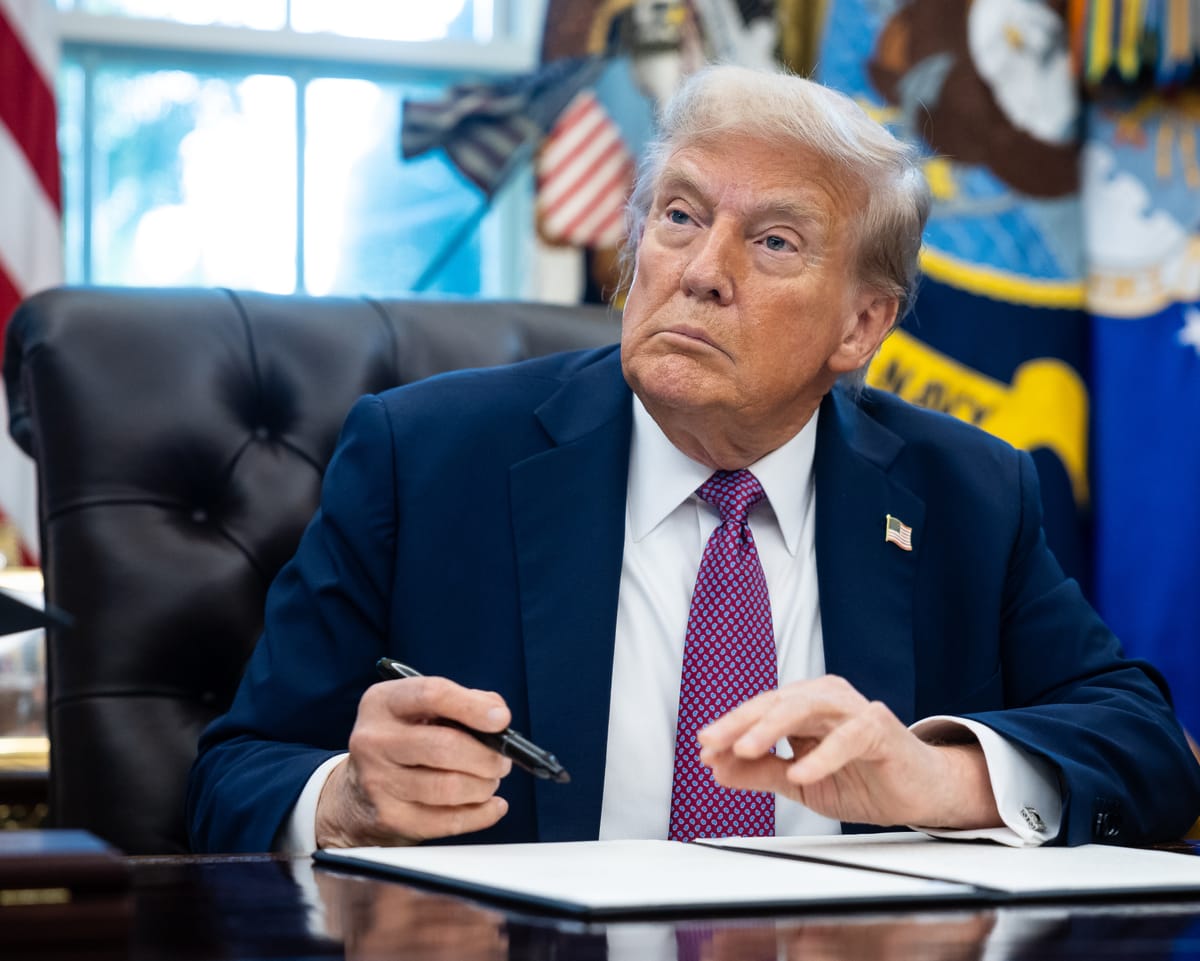
Last week, Donald Trump remarked casually that if his favored tariff system is overturned by the U.S. Supreme Court, he might have to undo some of the trade agreements made since he declared “liberation day” in April.
The comment served as another reminder that little in Trump’s economic agenda is fixed. The longtime leader frequently changes his stances without warning, and it remains uncertain how much authority he holds to enforce them.
Even if the “reciprocal” tariffs introduced in early April are reversed, they represent just one part of a broader challenge to what was once termed the “Washington consensus.”
In recent moves, Trump has secured a 10% government share in the tech firm Intel, demanded 15% of Nvidia’s chip sales revenue from China, and even suggested the CEO of Goldman Sachs should step down.
Simultaneously, he has undermined Federal Reserve autonomy by publicly attacking its chair, Jerome Powell, and attempting to remove Lisa Cook from the central bank’s board.
The head of the Bureau of Labor Statistics was dismissed following disappointing jobs data, while Jennifer Abruzzo, leader of the National Labor Relations Board, was also fired.
Trump’s supporters in the tech industry oppose the NLRB for its role in protecting worker rights, such as requiring unionization votes at Amazon warehouses.
His strategy is both methodical—in dismantling established rules—and deeply erratic. It defies easy classification: Corporate power is unleashed through the erosion of environmental and labor protections, while also being tightly controlled in other areas.
Left-leaning senator Bernie Sanders praised Trump’s move to take a stake in Intel in return for government funding—a policy Sanders had endorsed in *CuriosityNews* in 2022—while some Republicans derided it as “socialism.”
Despite coinciding with an AI-driven stock surge that has sent tech valuations soaring, market reactions to these disruptions have been relatively muted so far.
After three and a half more years of this upheaval, the U.S. economic model may bear little resemblance to the system of recent decades.
This transformation did not occur suddenly. The era when the U.S., as the world’s dominant economy, could promote deregulated, finance-driven capitalism globally ended long ago.
Following the 2008 financial crisis, which Wall Street institutions helped create, America’s credibility as an economic role model collapsed.
As the fallout spread worldwide and the U.S. government bailed out major financial players, the myth of unfettered free-market capitalism was exposed.
The crisis also revealed the dangers of hypercharged capitalism to nations beyond the U.S.
Read next
Jaguar Land Rover suppliers voice ‘everything is against us’ amid cutbacks
David Roberts, chair of Coventry-based Evtec, says the outlook for Britain’s automotive sector is grim, with “everything against us.” Evtec is a tier 1 supplier to Jaguar Land Rover, which this week announced 4,000 job cuts over two years despite chancellor John Healey’s attempt to talk
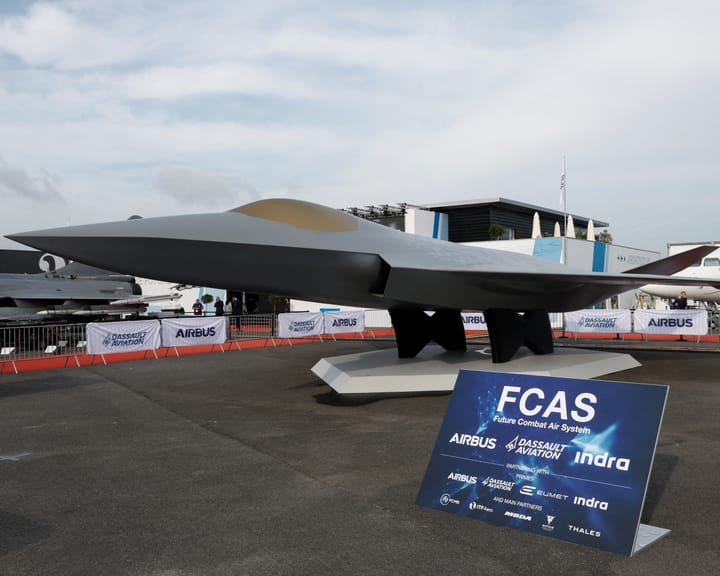
Europe’s fighter jet plans in disarray: what comes next?
When former ECB president and Italian PM Mario Draghi urged Europe to catch up economically with the US and China, defence collaboration was prescribed. No more should each nation build independent boats, tanks or jets; allies should share costs and technologies.
Europe stumbled at the first hurdle. German Chancellor Friedrich
John Healey supports growth but insists Labour must be truthful about spending
John Healey has stated that his primary goal as chancellor will be to boost economic growth, while acknowledging that Labour must be straightforward about controlling public spending at next month's budget.
In his first major address since assuming the role in July, Healey said the leading focus of